Northern Virginia Real Estate and Community News

July 29, 2022

Three Reasons To Buy a Home in Today’s Shifting Market

Three Reasons To Buy a Home in Today’s Shifting Market [INFOGRAPHIC] | MyKCM

Some Highlights

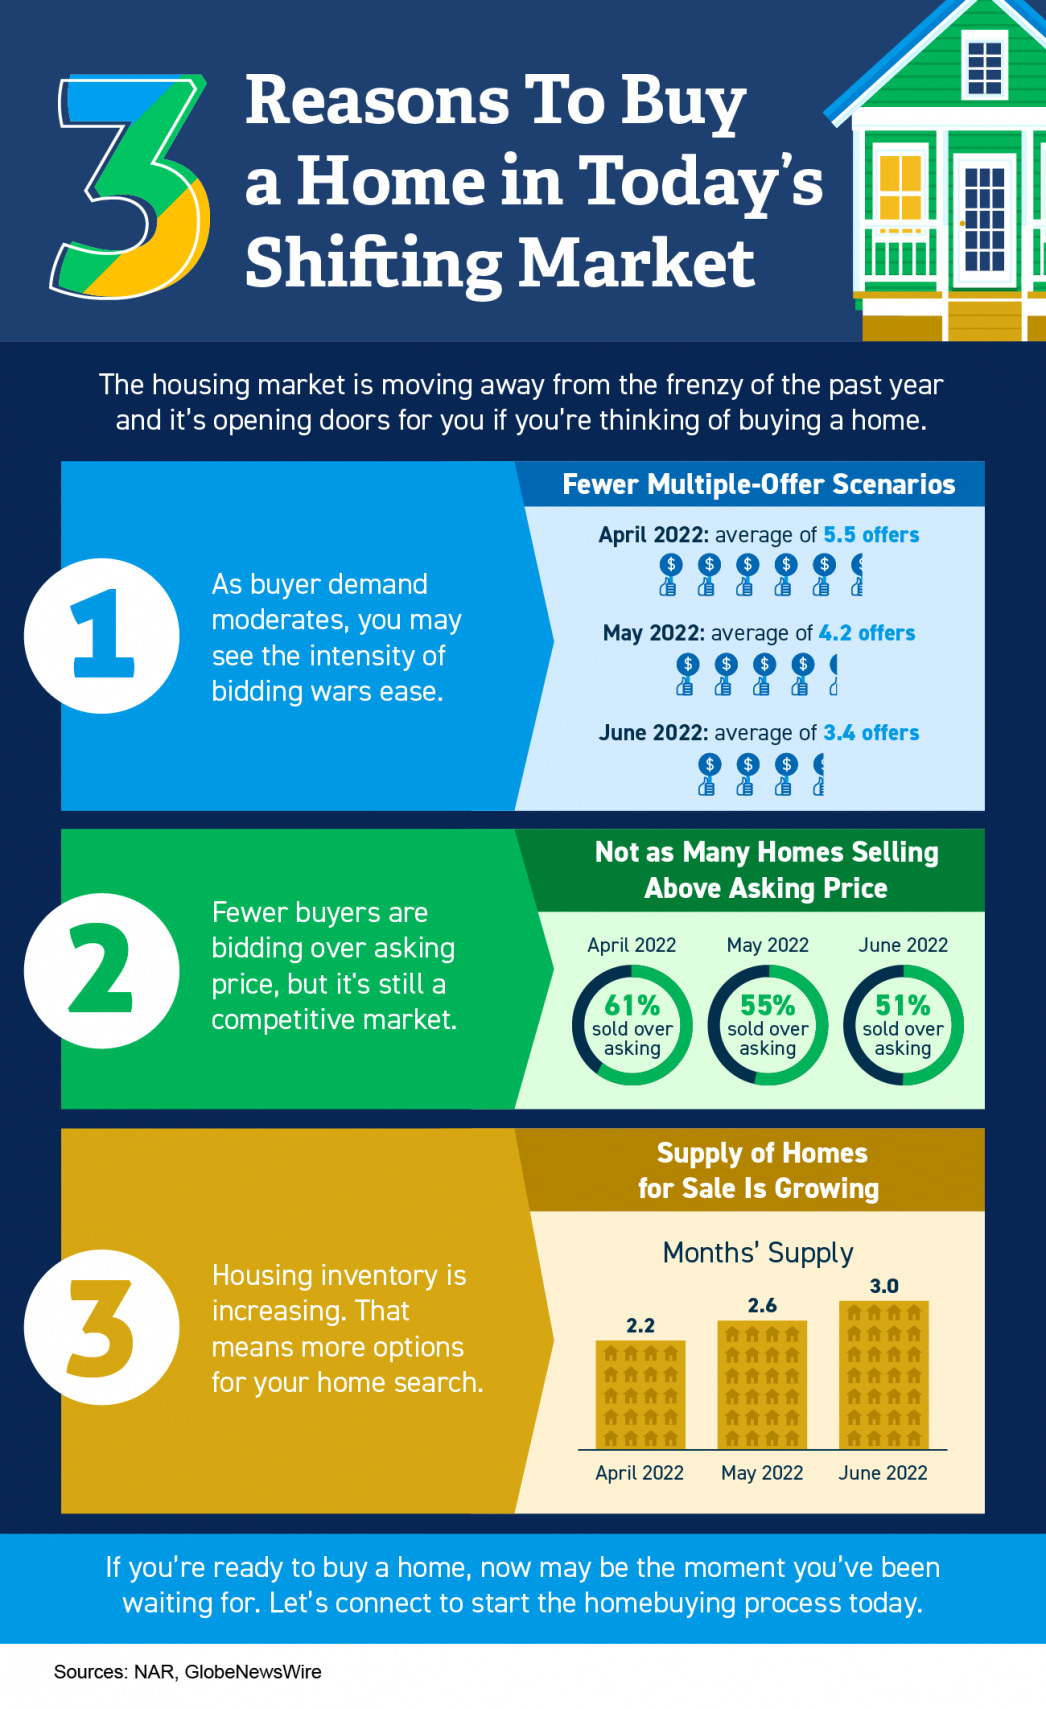
  • The housing market is moving away from the frenzy of the past year and it’s opening doors for you if you’re thinking about buying a home.
  • Housing inventory is increasing, which means more options for your search. Plus, the intensity of bidding wars may ease as buyer demand moderates, leading to fewer homes selling above asking price.
  • If you’re ready to buy a home, now may be the moment you’ve been waiting for. Let’s connect to start the homebuying process today.
July 28, 2022

A Real Estate Professional Helps You Separate Fact from Fiction

A Real Estate Professional Helps You Separate Fact from Fiction | MyKCM

If you’re following the news, chances are you’ve seen or heard some headlines about the housing market that don’t give the full picture. The real estate market is shifting, and when that happens, it can be hard to separate fact from fiction. That’s where a trusted real estate professional comes in. They can help debunk the headlines so you can really understand today’s market and what it means for you.

Here are three common housing market myths you might be hearing, along with the expert analysis that provides better context.

Myth 1: Home Prices Are Going To Fall

One piece of fiction many buyers may have seen or heard is that home prices are going to crash. That’s because headlines often use similar, but different, terms to describe what’s happening with prices. A few you might be seeing right now include:

  • Appreciation, or an increase in home prices.
  • Depreciation, or a decrease in home prices.
  • And deceleration, which is an increase in home prices, but at a slower pace.

The fact is, experts aren’t calling for a decrease in prices. Instead, they forecast appreciation will continue, just at a decelerated pace. That means home prices will continue rising and won’t fall. Selma Hepp, Deputy Chief Economist at CoreLogic, explains:

“. . . higher mortgage rates coupled with more inventory will lead to slower home price growth but unlikely declines in home prices.”

Myth 2: The Housing Market Is in a Correction

Another common myth is that the housing market is in a correction. Again, that’s not the case. Here’s why. According to Forbes:

“A correction is a sustained decline in the value of a market index or the price of an individual asset. A correction is generally agreed to be a 10% to 20% drop in value from a recent peak.

As mentioned above, home prices are still appreciating, and experts project that will continue, just at a slower pace. That means the housing market isn’t in a correction because prices aren’t falling. It’s just moderating compared to the last two years, which were record-breaking in nearly every way.

Myth 3: The Housing Market Is Going To Crash

Some headlines are generating worry that the housing market is a bubble ready to burst. But experts say today is nothing like 2008. One of the reasons why is because lending standards are very different today. Logan Mohtashami, Lead Analyst for HousingWire, explains:

“As recession talk becomes more prevalent, some people are concerned that mortgage credit lending will get much tighter. This typically happens in a recession, however, the notion that credit lending in America will collapse as it did from 2005 to 2008 couldn’t be more incorrect, as we haven’t had a credit boom in the period between 2008-2022.”

During the last housing bubble, it was much easier to get a mortgage than it is today. Since then, lending standards have tightened significantly, and purchasers who acquired a mortgage over the last decade are much more qualified than they were in the years leading up to the crash.

Bottom Line

No matter what you’re hearing about the housing market, let’s connect. That way, you’ll have a knowledgeable authority on your side that knows the ins and outs of the market, including current trends, historical context, and so much more.
July 26, 2022

A Window of Opportunity for Homebuyers

A Window of Opportunity for Homebuyers | MyKCM

Mortgage rates are much higher today than they were at the beginning of the year, and that’s had a clear impact on the housing market. As a result, the market is seeing a shift back toward the range of pre-pandemic levels for buyer demand and home sales.

But the transition back toward pre-pandemic levels isn’t a bad thing. In fact, the years leading up to the pandemic were some of the best the housing market has seen. That’s why, as the market undergoes this shift, it’s important to compare today not to the abnormal pandemic years, but to the most recent normal years to show how the current housing market is still strong.

Higher Mortgage Rates Are Moderating the Housing Market 

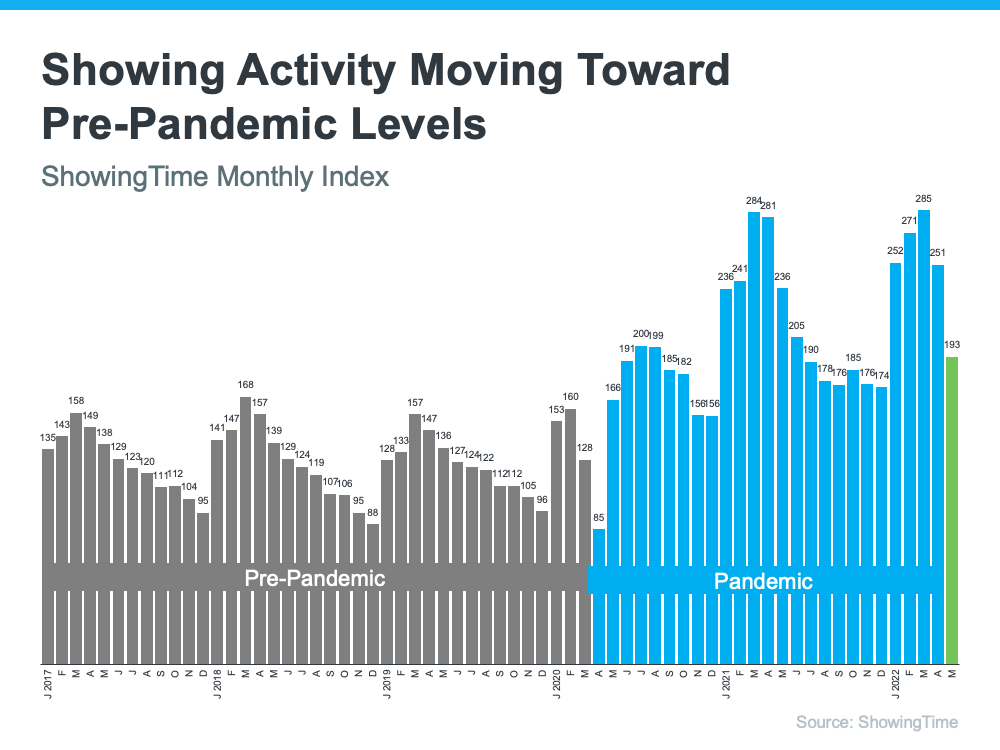
The ShowingTime Showing Index tracks the traffic of home showings according to agents and brokers. It’s also a good indication of buyer demand over time. Here’s a look at their data going back to 2017 (see graph below):

A Window of Opportunity for Homebuyers | MyKCM

Here’s a breakdown of the story this data tells:

  • The 2017 through early 2020 numbers (shown in gray) give a good baseline of pre-pandemic demand. The steady up and down trends seen in each of these years show typical seasonality in the market.
  • The blue on the graph represents the pandemic years. The height of those blue bars indicates home showings skyrocketed during the pandemic.
  • The most recent data (shown in green), indicates buyer demand is moderating back toward more pre-pandemic levels.

This shows that buyer demand is coming down from levels seen over the past two years, and the frenzy in real estate is easing because of higher mortgage rates. For you, that means buying your next home should be less challenging than it would’ve been during the pandemic because there is more inventory available.

Higher Mortgage Rates Slow the Once Frenzied Pace of Home Sales

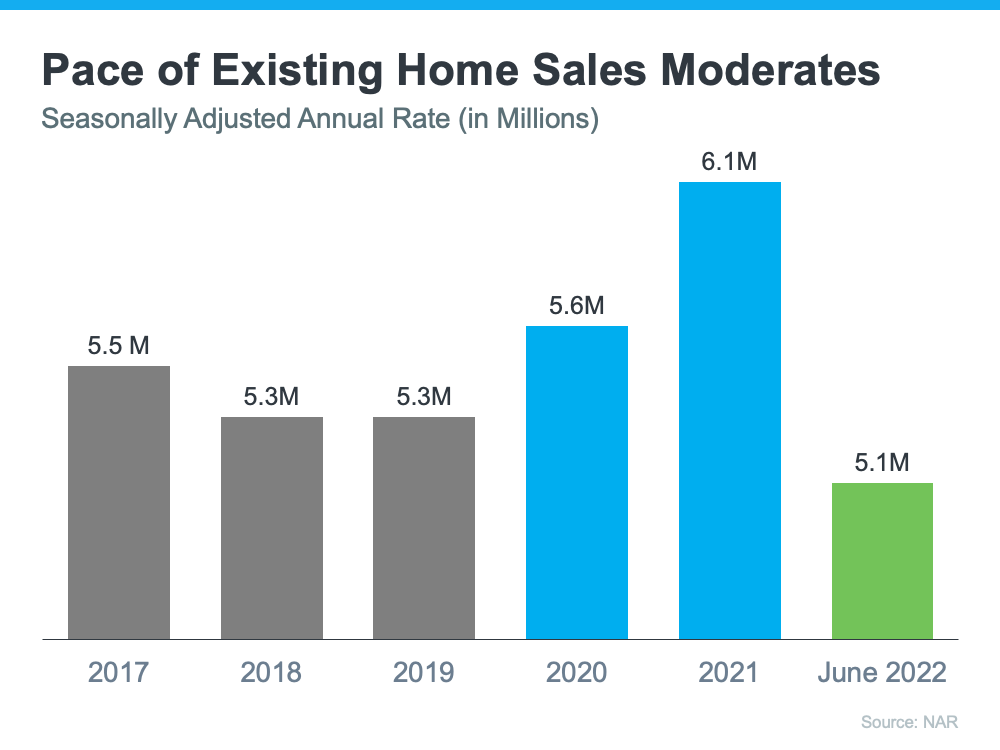
As mortgage rates started to rise this year, other shifts began to occur too. One additional example is the slowing pace of home sales. Using data from the National Association of Realtors (NAR), here’s a look at existing home sales going all the way back to 2017. Much like the previous graph, a similar trend emerges (see graph below):

A Window of Opportunity for Homebuyers | MyKCM

Again, the data paints a picture of the shift:

  • The pre-pandemic years (shown in gray) establish a baseline of the number of existing home sales in more typical years.
  • The pandemic years (shown in blue) exceeded the level of sales seen in previous years. That’s largely because low mortgage rates during that time spurred buyer demand and home sales to new heights.
  • This year (shown in green), the market is feeling the impact of higher mortgage rates and that’s moderating buyer demand (and by extension home sales). That’s why the expectation for home sales this year is closer to what the market saw in 2018-2019.

Why Is All of This Good News for You?

Both of those factors have opened up a window of opportunity for homeowners looking to move and for buyers looking to purchase a home. As demand moderates and the pace of home sales slows, housing inventory is able to grow – and that gives you more options for your home search.

So don’t let the headlines about the market cooling or moderating scare you. The housing market is still strong; it’s just easing off from the unsustainable frenzy it saw during the height of the pandemic – and that’s a good thing. It opens up new opportunities for you to find a home that meets your needs.

Bottom Line

The housing market is undergoing a shift because of higher mortgage rates, but the market is still strong. If you’ve been looking to buy a home over the last couple of years and it felt impossible to do, now may be your opportunity. Buying a home right now isn’t easy, but there is more opportunity for those who are looking.

July 20, 2022

Should You Buy a Home with Inflation This High?

Should You Buy a Home with Inflation This High? | MyKCM

While the Federal Reserve is working hard to bring down inflation, the latest data shows the inflation rate is still going up. You no doubt are feeling the pinch on your wallet at the gas pump or the grocery store, but that news may also leave you wondering: should I still buy a home right now?

Greg McBride, Chief Financial Analyst at Bankrateexplains how inflation is affecting the housing market:

Inflation will have a strong influence on where mortgage rates go in the months ahead. . . . Whenever inflation finally starts to ease, so will mortgage rates — but even then, home prices are still subject to demand and very tight supply.”

No one knows how long it’ll take to bring down inflation, and that means the future trajectory of mortgage rates is also unclear. While that uncertainty isn’t comfortable, here’s why both inflation and mortgage rates are important for you and your homeownership plans.

When you buy a home, the mortgage rate and the price of the home matter. Higher mortgage rates impact how much you’ll pay for your monthly mortgage payment – and that directly affects how much you can comfortably afford. And while there’s no denying it’s more expensive to buy and finance a home this year than it was last year, it doesn’t mean you should pause your search. Here’s why.

Homeownership Is Historically a Great Hedge Against Inflation

In an inflationary economy, prices rise across the board. Historically, homeownership is a great hedge against those rising costs because you can lock in what’s likely your largest monthly payment (your mortgage) for the duration of your loan. That helps stabilize some of your monthly expenses. Not to mention, as home prices continue to appreciate, your home’s value will too. That’s why Mark Cussen, Financial Writer at Investopediasays: 

Real estate is one of the time-honored inflation hedges. It's a tangible asset, and those tend to hold their value when inflation reigns, unlike paper assets. More specifically, as prices rise, so do property values.”

Also, no one is calling for homes to lose value. As Selma Hepp, Deputy Chief Economist at CoreLogicsays:

“The current home price growth rate is unsustainable, and higher mortgage rates coupled with more inventory will lead to slower home price growth but unlikely declines in home prices.”

In a nutshell, your home search doesn’t have to go on hold because of rising inflation or higher mortgage rates. There’s more to consider when it comes to why you want to buy a home. In addition to shielding yourself from the impact of inflation and growing your wealth through ongoing price appreciation, there are other reasons to buy a home right now like addressing your changing needs and so much more.

Bottom Line

Homeownership is one of the best decisions you can make in an inflationary economy. You get the benefit of the added security of owning your home in a time when experts are forecasting prices to continue to rise.

July 19, 2022

Why Pre-Approval Is a Game Changer for Homebuyers

Why Pre-Approval Is a Game Changer for Homebuyers | MyKCM

If you’re planning to buy a home this year, you might have heard that pre-approval is a necessary step to take before starting out on your journey. But why is that? And is it still important in today’s shifting market?

The truth is, getting a pre-approval letter from your lender is critical, and when it comes to your home search, it can be a game changer in so many ways.

To better understand why, it’s important to know what pre-approval is. Freddie Mac defines the process like this:

“A pre-approval is an indication from your lender that they are willing to lend you a certain amount of money to buy your future home. The lender you work with will provide you with a pre-approval letter, which is an official document that states the maximum amount they are willing to lend you, . . .”

Put simply, pre-approval from a lender helps you understand your true price range and how much money you can borrow for your loan. That can make it easier when you set out to search for homes. And since you’ll know what you’re approved for, it’ll also help once it’s time to submit an offer on the home of your dreams.

Another added benefit is that pre-approval lets the seller know you’re qualified to buy their house. Paul Centopani, Editor for the Mortgage Reportsexplains:

“. . . most sellers won’t even consider an offer unless the buyer is pre-approved at the right price point. Sellers and their agents want to know you’re ready and able to finance your offer amount. So you’ll want to have your preapproval teed up as soon as you’re serious about bidding on a home you like.”

Every advantage you can gain as a buyer is crucial in a market that’s constantly changing. You’re going to need guidance to navigate these waters, so it’s important to have a team of professionals, such as a real estate advisor and trusted lender, on your side. They’ll help make sure you’re ready to put your best foot forward.

Bottom Line

Getting pre-approved for a mortgage helps you better understand what you can borrow and shows sellers you’re serious about purchasing their home. Let’s connect so you have the tools you need to succeed as a homebuyer in today’s shifting market.

Posted in Buying a Home
July 15, 2022

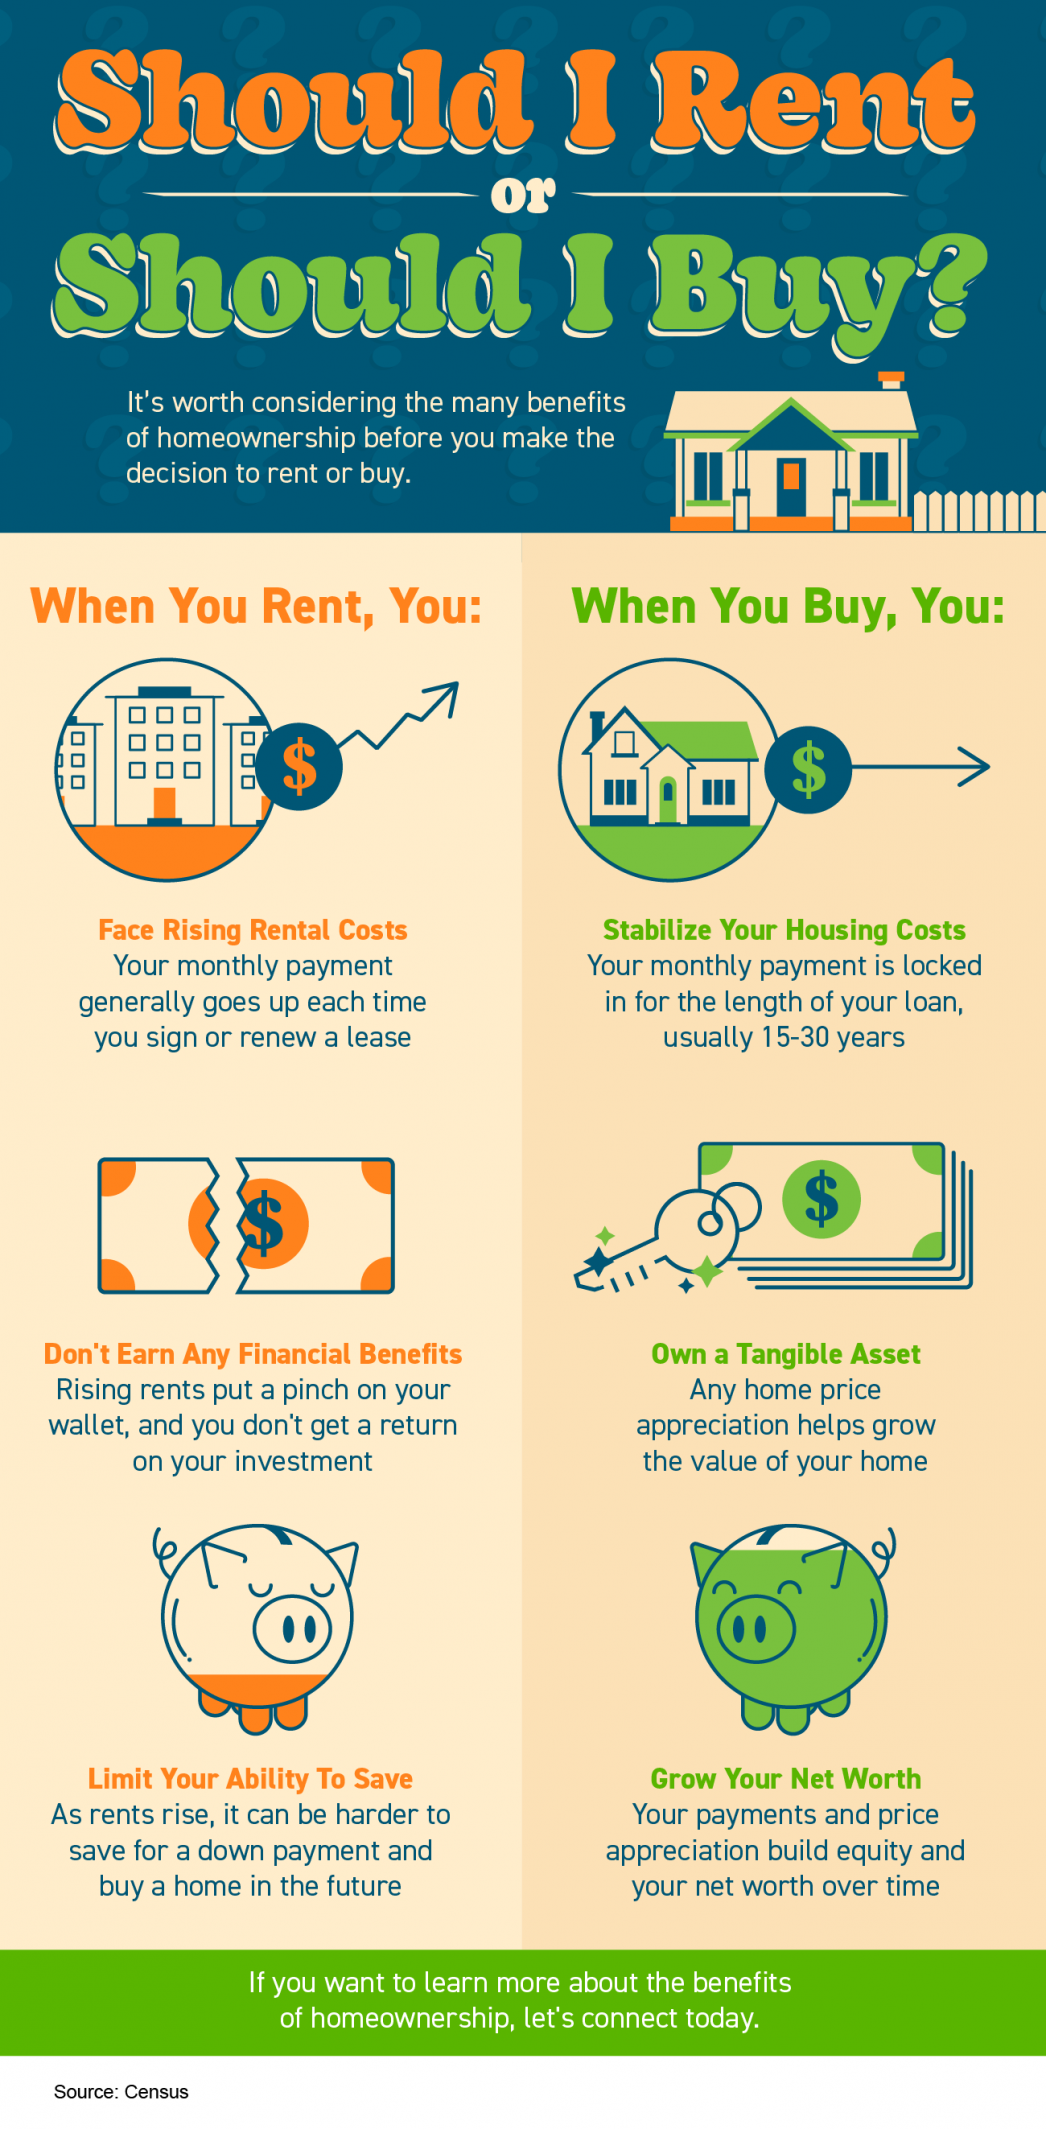
Should I Rent or Should I Buy?

Should I Rent or Should I Buy? [INFOGRAPHIC] | MyKCM

Some Highlights

  • It’s worth considering the many benefits of homeownership before you make the decision to rent or buy a home.
  • When you buy, you can stabilize your housing costs, own a tangible asset, and grow your net worth as you gain equity. When you rent, you face rising housing costs, won’t see a return on your investment, and limit your ability to save.
  • If you want to learn more about the benefits of homeownership, let’s connect today.
Posted in Buying a Home
July 11, 2022

The Drop in Mortgage Rates Brings Good News for Homebuyers

The Drop in Mortgage Rates Brings Good News for Homebuyers | MyKCM

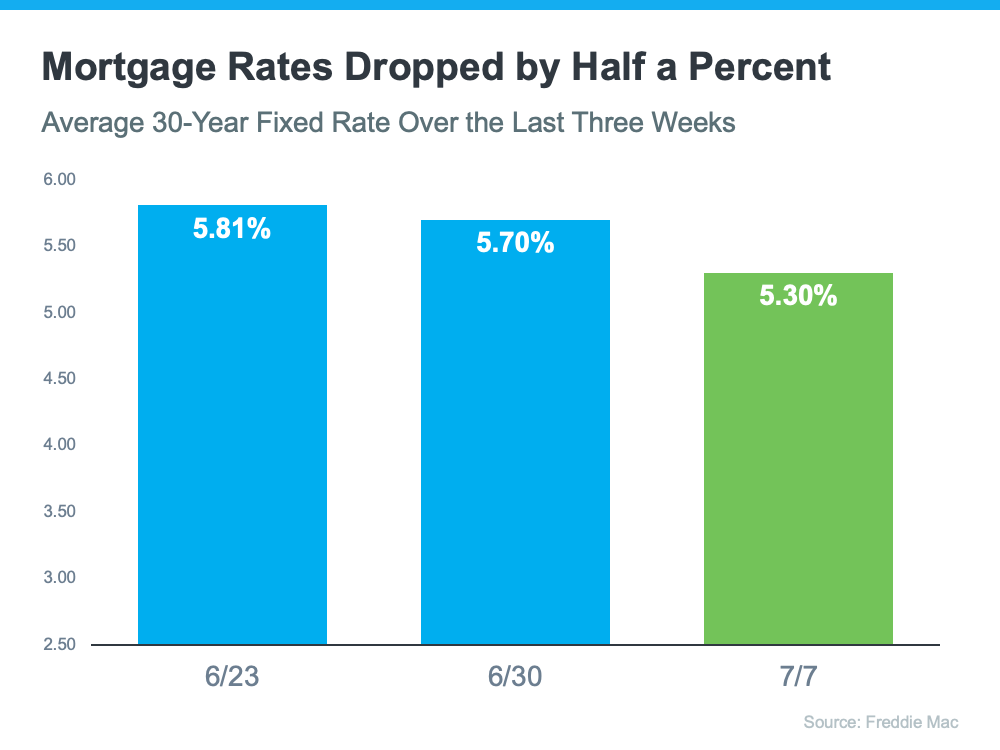
Over the past few weeks, the average 30-year fixed mortgage rate from Freddie Mac fell by half a percent. The drop happened over concerns about a potential recession. And since mortgage rates have risen dramatically this year, homebuyers across the country should see this decline as welcome news.

Freddie Mac reports that the average 30-year rate was down to 5.30% from 5.81% two weeks prior (see graph below):

The Drop in Mortgage Rates Brings Good News for Homebuyers | MyKCM

But why is this recent dip such good news for homebuyers? As Nadia Evangelou, Senior Economist and Director of Forecasting at the National Association of Realtors (NAR), explains:

“According to Freddie Mac, the 30-year fixed mortgage rate dropped sharply by 40 basis points to 5.3 percent. . . . As a result, home buying is about 5 percent more affordable than a week ago. This translates to about $100 less every month on a mortgage payment.

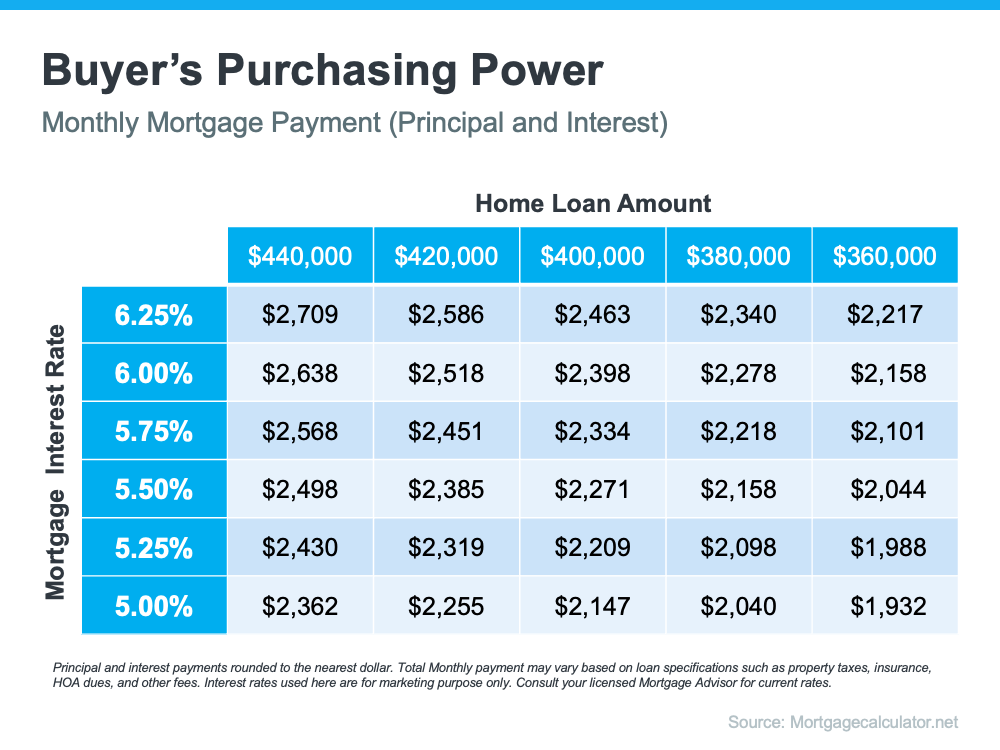
That’s because when rates go up (as they have for the majority of this year), they impact how much you’ll pay in your monthly mortgage payment, which directly affects how much you can comfortably afford. The inverse is also true. A decrease in mortgage rates means an increase in your purchasing power.

The chart below shows how a half-point, or even a quarter-point, change in mortgage rates can impact your monthly payment:

The Drop in Mortgage Rates Brings Good News for Homebuyers | MyKCM

Bottom Line

If your home doesn’t meet your needs, this may be the opportunity you’ve been waiting for. Let’s connect to see how you can benefit from the current drop in mortgage rates.


Posted in Buying a Home
July 7, 2022

What Does an Economic Slowdown Mean for the Housing Market?

What Does an Economic Slowdown Mean for the Housing Market? | MyKCM

According to a recent survey, more and more Americans are concerned about a possible recession. Those concerns were validated when the Federal Reserve met and confirmed they were strongly committed to bringing down inflation. And, in order to do so, they’d use their tools and influence to slow down the economy.

All of this brings up many fears and questions around how it might affect our lives, our jobs, and business overall. And one concern many Americans have is: how will this affect the housing market? We know how economic slowdowns have impacted home prices in the past, but how could this next slowdown affect real estate and the cost of financing a home?

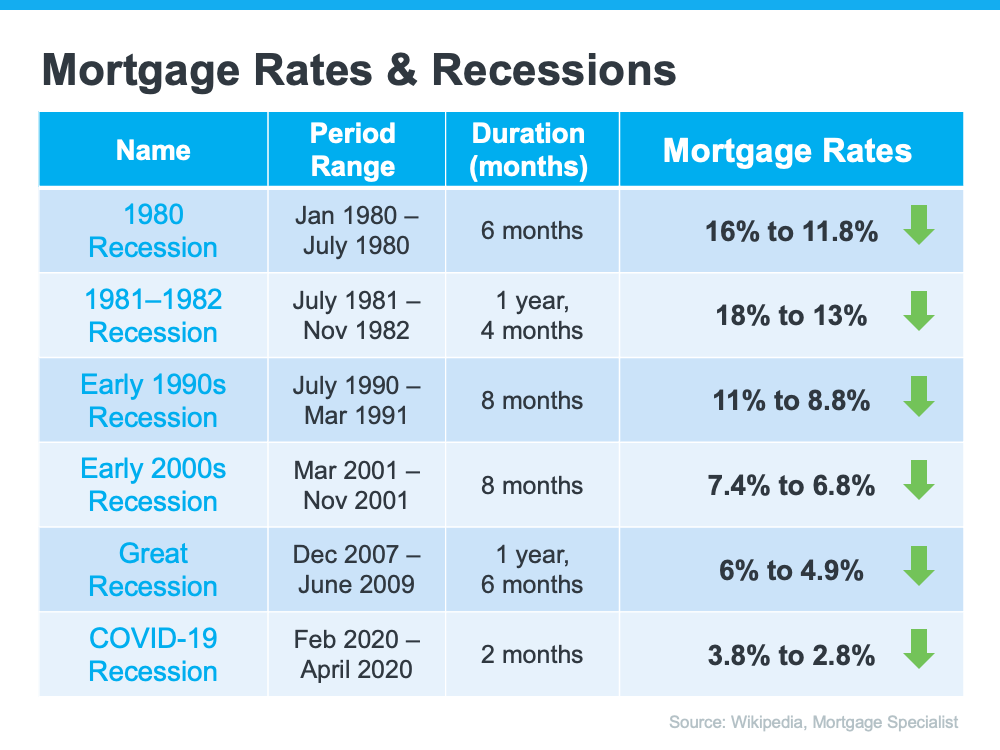
According to Mortgage Specialists: 

Throughout history, during a recessionary period, interest rates go up at the beginning of the recession. But in order to come out of a recession, interest rates are lowered to stimulate the economy moving forward.”

Here’s the data to back that up. If you look back at each recession going all the way to the early 1980s, here’s what happened to mortgage rates during those times (see chart below):

What Does an Economic Slowdown Mean for the Housing Market? | MyKCM

As the chart shows, historically, each time the economy slowed down, mortgage rates decreased. Fortune.com helps explain the trend like this:

“Over the past five recessions, mortgage rates have fallen an average of 1.8 percentage points from the peak seen during the recession to the trough. And in many cases, they continued to fall after the fact as it takes some time to turn things around even when the recession is technically over.”

And while history doesn’t always repeat itself, we can learn from it. While an economic slowdown needs to happen to help taper inflation, it hasn’t always been a bad thing for the housing market. Typically, it has meant that the cost to finance a home has gone down, and that’s a good thing. 

Bottom Line

Concerns of a recession are rising. As the economy slows down, history tells us this would likely mean lower mortgage rates for those looking to refinance or buy a home. While no one knows exactly what the future holds, you can make the right decision for you by working with a trusted real estate professional to get expert advice on what’s happening in the housing market and what that means for your homeownership goals.

July 6, 2022

How Your Equity Can Grow over Time

How Your Equity Can Grow over Time | MyKCM

It’s true that record levels of home price appreciation have spurred significant equity gains for homeowners over the past few years. As Diana Olick, Real Estate Correspondent at CNBC, says:

“The stunning jump in home values over the course of the Covid-19 pandemic has given U.S. homeowners record amounts of housing wealth.”

That’s great for your home’s value over the last couple of years, but what if you’ve lived in your home for longer than that? You may be wondering how much equity you truly have.

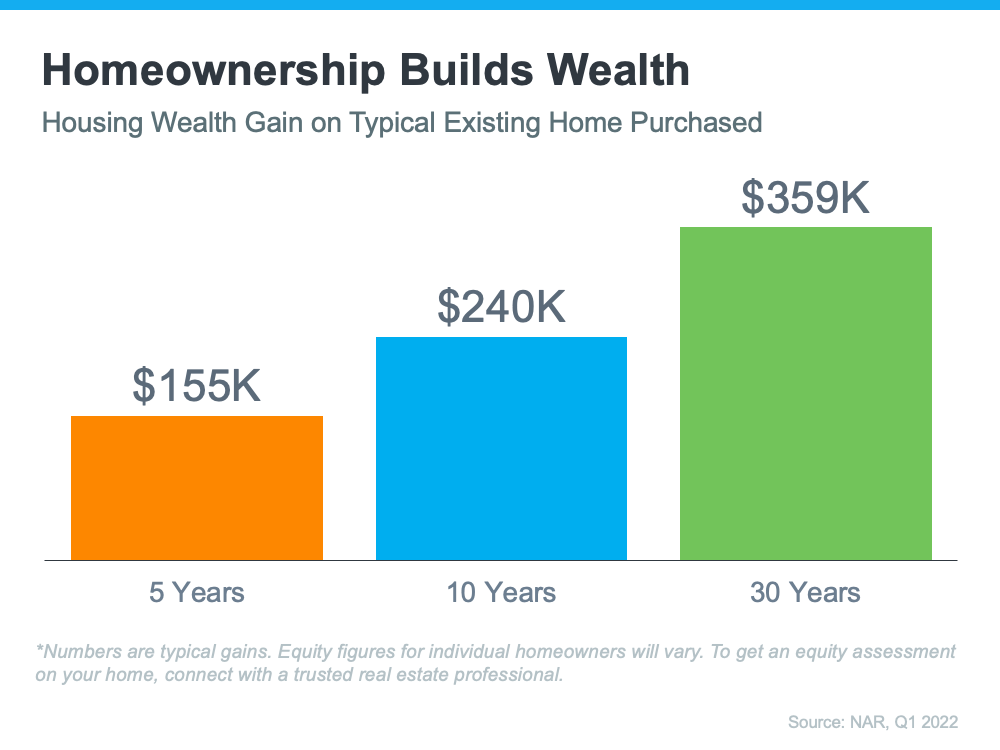
The National Association of Realtors (NAR) has done a study to calculate the typical equity gains over longer spans of time. The data they compiled could be enough to motivate you to move. Just remember, to find out how much equity you have in your specific home, you’ll want to get a professional equity assessment from a trusted real estate advisor.

How Your Equity Grows

Let’s start by establishing how you build equity in your home. While price appreciation is clearly a factor that can help boost your equity, you also build equity over time as you pay down your home loan. NAR explains:

Home equity gains are built up through price appreciation and by paying off the mortgage through principal payments.

Average Equity Growth over Time

The study from NAR breaks down the typical equity gain over time (see graph below). It calculates the equity a homeowner potentially gained if they purchased the median-priced home 5, 10, or 30 years ago and still own it today.

How Your Equity Can Grow over Time | MyKCM

These six-figure numbers are impressive and certainly enough to help you fuel a move into your next home, but they’re not a promised amount. Remember, your own equity gain will be different. It depends on how long you’ve been in the house, your home’s condition, any upgrades you’ve made, your area, and much more.

If you want to find out how much equity you have, partner with a trusted real estate professional for an equity assessment on your home. They can provide an expert opinion on what your house is worth today and how the equity you’ve gained over time can help you when you purchase your next home. It may be some (if not all) of what you need for your next down payment.

Bottom Line

If you’re thinking about selling your house and making a move, home equity can be a real game-changer, especially if you’ve been in your current home for a while. If you’re ready to find out how much equity you have, let’s connect.

Posted in Buying a Home
July 5, 2022

Is Homeownership Still the American Dream?

Is Homeownership Still the American Dream? | MyKCM

Defining the American dream is personal, and no one individual will have the same definition as another. But the feelings it brings about – success, freedom, and a sense of prosperity – are universal. That’s why, for many people, homeownership remains a key part of the American dream. Your home is your stake in the community, a strong financial investment, and an achievement to be proud of.

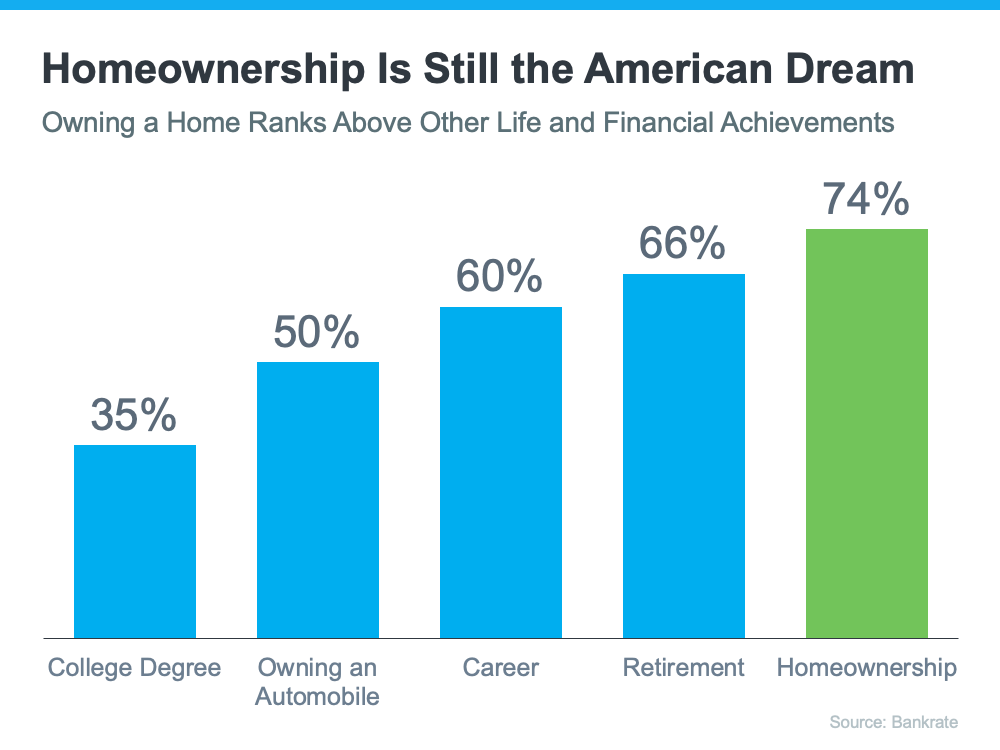
A recent survey from Bankrate asked respondents to rank achievements as indicators of financial success, and the responses prove that owning a home is still important to so many Americans today (see graph below):

Is Homeownership Still the American Dream? | MyKCM

As the graph shows, homeownership ranks above other significant milestones, including retirement, having a successful career, and earning a college degree.

That could be because owning a home is a significant wealth-building tool and provides meaningful financial stability. The National Association of Realtors (NAR) explains:

Homeownership builds financial security. With 65.5% of Americans owning homes, the net worth of a typical homeowner is nearly 40 times the net worth of a non-owner.”

There are other ways your home acts as more than just a roof over your head, too. The Mortgage Reports highlights a few of the many benefits homeowners enjoy, including:

  • Your equity (and wealth) grows through home price appreciation.
  • Your housing costs are fixed – and that can help combat rising costs from inflation.
  • You’ll have greater privacy and the opportunity to customize your living space.

Plus, homeowners tend to be more active in their community. Like NAR says:

“Living in one place for a longer amount of time creates and [sic] obvious sense of community pride, which may lead to more investment in said community.”

What Does That Mean for You?

If your definition of the American Dream involves greater freedom and prosperity, then homeownership could play a major role in helping you achieve that dream. When you set out to buy, know there are incredible benefits waiting for you at the end of your journey. You’ll have a place you can call your own, feel most comfortable, and grow your wealth.

First American puts it best, saying:

Homeownership remains central to the pursuit of the American Dream. It is a critical driver of economic mobility, delivering financial and social advantages. . . .”

Bottom Line

Buying a home is a powerful decision and a key part of the American Dream. And if homeownership is part of your personal dreams this year, let’s connect and start the process today.