Northern Virginia Real Estate and Community News

Dec. 29, 2021

5 Tips for Making Your Best Offer on a Home

5 Tips for Making Your Best Offer on a Home | MyKCM

As a buyer in a sellers’ market, sometimes it can feel like you’re stuck between a rock and a hard place. When you’re ready to make an offer on a home, remember these five easy tips to help you rise above the competition.

1. Know Your Budget

Knowing your budget and what you can afford is critical to your success as a homebuyer. The best way to understand your numbers is to work with a lender so you can get pre-approved for a loan. As Freddie Mac puts it:

“This pre-approval allows you to look for a home with greater confidence and demonstrates to the seller that you are a serious buyer.”

Showing sellers you’re serious can give you a competitive edge, and it helps you act quickly when you’ve found your perfect home.

2. Be Ready To Move Fast

Homes are selling quickly in today’s competitive housing market. According to the Existing Home Sales Report from the National Association of Realtors (NAR):

“Eighty-three percent of homes sold in November 2021 were on the market for less than a month.”

When houses are selling this fast, staying on top of the market and moving quickly are key. Your agent can help you put together and submit your best offer as soon as you find the home you want to buy.

3. Lean on a Real Estate Professional

No matter what the housing market looks like, rely on a trusted real estate advisor. As Freddie Mac also notes:

“The success of your homebuying journey largely depends on the company you keep. . . . Be sure to select experienced, trusted professionals who will help you make informed decisions and avoid any pitfalls.”

Agents are experts in the local real estate market. They have insight into what’s worked for other buyers in your area and what sellers may be looking for in an offer. It may seem simple, but catering to what a seller needs can help your offer stand out.

4. Make a Strong, but Fair Offer

According to the latest Realtors Confidence Index from NAR, 40% of offers today are above the list price. In such a competitive market, emotions and prices can run high. Having an agent to help you submit a strong, yet fair offer is critical in these situations. Your agent can help you understand the market value of the home and recent sales trends in the area.

5. Be a Flexible Negotiator

When putting together an offer, your trusted real estate advisor will help you consider which levers you can pull, including contract contingencies (conditions you set that the seller must meet for the purchase to be finalized). Of course, there are certain contingencies you don’t want to give up. Freddie Mac explains:

“Resist the temptation to waive the inspection contingency, especially in a hot market or if the home is being sold ‘as-is’, which means the seller won’t pay for repairs. Without an inspection contingency, you could be stuck with a contract on a house you can’t afford to fix.”

Bottom Line

Today’s competitive landscape makes it more important than ever to make a strong offer on a home. Let’s connect to make sure you rise to the top along the way.
Posted in Buying a Home
Dec. 28, 2021

When a House Becomes a Home

When a House Becomes a Home | MyKCM

It’s clear that owning a home makes financial sense. But lately, the emotional side of what drives homeownership is becoming increasingly important.

No matter the living space, the feeling of a home means different things to different people. Whether it’s a familiar scent or a favorite chair, the feel-good connections to our own homes can be more important to us than the financial ones. Here are some of the reasons why.

1. Owning your home is an accomplishment worth celebrating

You’ve put in a lot of work to achieve the dream of homeownership, and whether it’s your first home or your fifth, congratulations are in order for this milestone. You’ve earned it.

2. There’s no place like home

Owning your own home offers not only safety and security but also a comfortable place where you can simply relax and unwind after a long day. Sometimes that’s just what we need to feel recharged and truly content.

3. You can find more space to meet your needs

Whether you want more room for your changing lifestyle (think: working from home, dedicated space for a hobby, or a personal gym) or you simply prefer to have a large backyard for entertaining, you can invest in a home that truly works for your evolving needs.

4. You have control over renovations, updates, and your style

Looking to try one of those decorative wall treatments you saw on Pinterest? Tired of paying an additional pet deposit for your apartment building? Maybe you want to create an entire in-home yoga studio. You can do all of these things in your own home.

Bottom Line

Whether you’re a first-time homebuyer or a repeat buyer who’s ready to start a new chapter in your life, now is a great time to reflect on the non-financial factors that turn a house into a happy home.


Posted in Buying a Home
Dec. 27, 2021

Key Things To Avoid After Applying for a Mortgage

Key Things To Avoid After Applying for a Mortgage | MyKCM

Once you’ve found your dream home and applied for a mortgage, there are some key things to keep in mind before you close. It’s exciting to start thinking about moving in and decorating your new place, but before you make any large purchases, move your money around, or make any major life changes, be sure to consult your lender – someone who’s qualified to explain how your financial decisions may impact your home loan.

Here’s a list of things you shouldn’t do after applying for a mortgage. They’re all important to know – or simply just good reminders – for the process.

1. Don’t Deposit Cash into Your Bank Accounts Before Speaking with Your Bank or Lender.

Lenders need to source your money, and cash isn’t easily traceable. Before you deposit any amount of cash into your accounts, discuss the proper way to document your transactions with your loan officer.

2. Don’t Make Any Large Purchases Like a New Car or Furniture for Your Home.

New debt comes with new monthly obligations. New obligations create new qualifications. People with new debt have higher debt-to-income ratios. Since higher ratios make for riskier loans, qualified borrowers may end up no longer qualifying for their mortgage.

3. Don’t Co-Sign Other Loans for Anyone.

When you co-sign, you’re obligated. With that obligation comes higher debt-to-income ratios as well. Even if you promise you won’t be the one making the payments, your lender will have to count the payments against you.

4. Don’t Change Bank Accounts.

Remember, lenders need to source and track your assets. That task is much easier when there’s consistency among your accounts. Before you transfer any money, speak with your loan officer.

5. Don’t Apply for New Credit.

It doesn’t matter whether it’s a new credit card or a new car. When you have your credit report run by organizations in multiple financial channels (mortgage, credit card, auto, etc.), your FICO® score will be impacted. Lower credit scores can determine your interest rate and possibly even your eligibility for approval.

6. Don’t Close Any Credit Accounts.

Many buyers believe having less available credit makes them less risky and more likely to be approved. This isn’t true. A major component of your score is your length and depth of credit history (as opposed to just your payment history) and your total usage of credit as a percentage of available credit. Closing accounts has a negative impact on both of those determinants of your score.

Bottom Line

Any blip in income, assets, or credit should be reviewed and executed in a way that ensures your home loan can still be approved. If your job or employment status has changed recently, share that with your lender as well. The best plan is to fully disclose and discuss your intentions with your loan officer before you do anything financial in nature.

Posted in Buying a Home
Dec. 23, 2021

The Average Homeowner Gained $56,700 in Equity over the Past Year

The Average Homeowner Gained over $56,700 in Equity over the Past Year | MyKCM

When you think of homeownership, what’s the first thing that comes to mind? Chances are you might focus on the non-financial benefits, like the security or stability a home provides. But what about equity? While it can be overlooked, a homeowner’s equity helps build long-term wealth over time. Here’s a look at what equity is and why it matters.

For a homeowner, your equity is the current value of your home minus what you owe on the loan. So, as home values climb, your equity does too. That’s exactly what’s happening today. There aren’t enough homes on the market to meet buyer demand, so bidding wars and multiple offers are driving prices up. That’s because people are willing to pay more to buy a home. Right now, this low supply and high demand are giving current homeowners a significant equity boost.

Dr. Frank Nothaft, Chief Economist at CoreLogic, explains it like this:

Home price growth is the principal driver of home equity creation. The CoreLogic Home Price Index reported home prices were up 17.7% for the past 12 months ending September, spurring the record gains in home equity wealth.

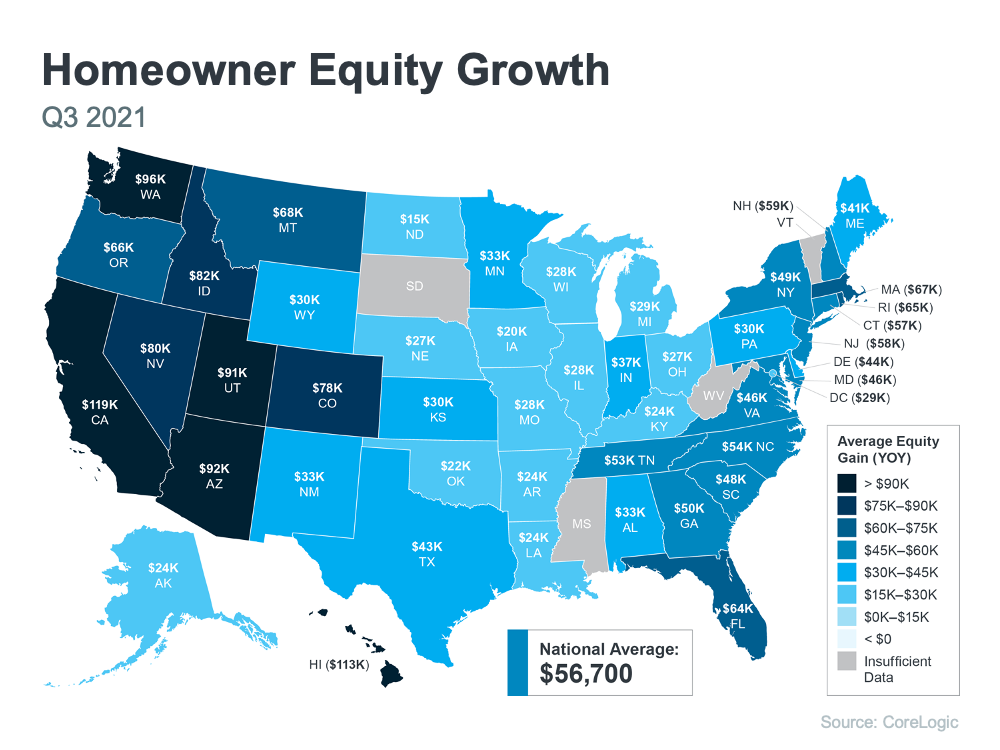
To find out just how much rising home values have impacted equity, we turn to the latest Homeowner Equity Insights from CoreLogic. According to that report, the average homeowner’s equity has grown by $56,700 over the last 12 months.

Curious how your state stacks up? Check out the map below to find out the average equity gain for your area.The Average Homeowner Gained over $56,700 in Equity over the Past Year | MyKCM

How Rising Equity Impacts You

If you’re already a homeowner, equity not only builds your wealth, it also opens doors for you to achieve your goals. It works like this: when you sell your house, the equity you built up comes back to you in the sale. You can use those proceeds to fuel your next move, especially if you’ve decided your needs have changed and you’re looking for something new.

If you’re thinking about becoming a homeowner, understanding the importance of equity can help you realize why homeownership is a worthwhile goal. It builds your wealth and gives you peace of mind that your investment is a wise one, not just from a lifestyle perspective, but from a financial one too.

Bottom Line

Whether you’re a current homeowner or you’re ready to become one, it’s important to know how equity works and why it matters. If this inspires you to make a move, let’s connect to explore your options and find out what steps you need to take next.

Dec. 22, 2021

Homebuyers: Be Ready To Act This Winter

Homebuyers: Be Ready To Act This Winter | MyKCM

To succeed as a buyer in today’s market, it’s important to understand which market trends will have the greatest impact on your home search. Danielle Hale, Chief Economist at realtor.comsays there are two factors every buyer should keep their eyes on:

“Going forward, the conditions buyers face are primarily dependent on two things: mortgage rates and housing supply.

Here’s a look at each one.

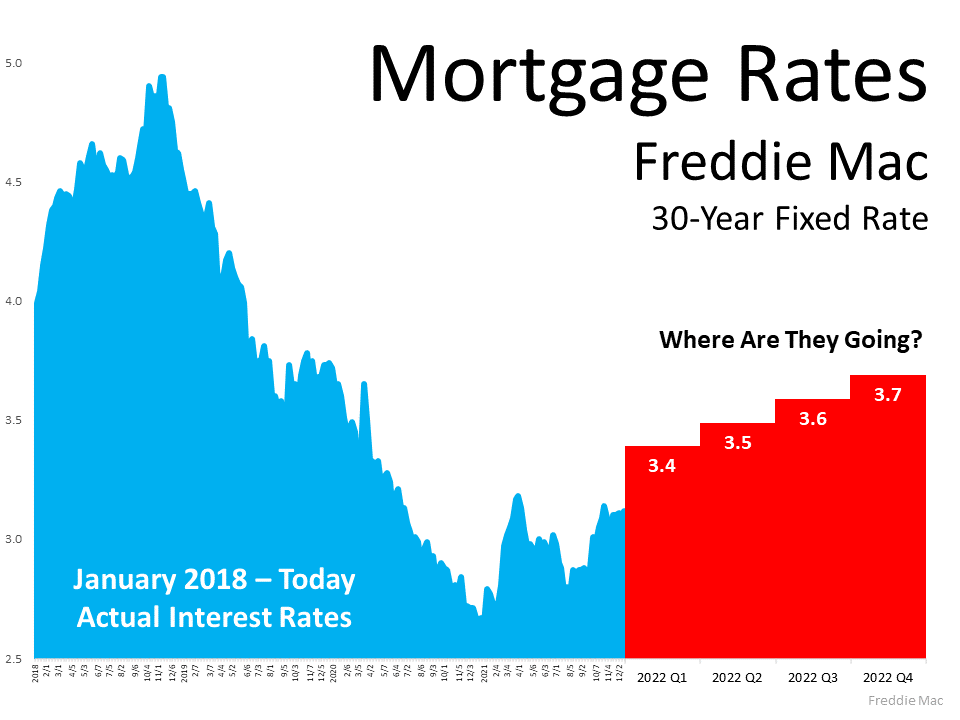
Mortgage Rates Projected To Rise in 2022

As a buyer, your interest rate directly impacts how much you’ll pay on your monthly mortgage when you purchase a home. Rates are beginning to rise, and experts forecast they’ll continue going up in 2022 (see graph below):Homebuyers: Be Ready To Act This Winter | MyKCMAs the graph shows, mortgage rates are expected to climb next year. But they’re still low when you compare to where they were just a few years ago. That presents today’s buyers with some motivation to lock in a low mortgage rate before they climb higher.

More Homes Are Expected To Be Available This Season

The other market condition buyers need to monitor is the number of homes available for sale today. The latest Existing Home Sales Report from the National Association of Realtors (NAR) shows the current supply of inventory sits at just 2.4-months. To put that into perspective, a 6-month supply is ideal for a balanced market where there are enough homes to meet buyer demand.

However, there may be good news for buyers who are waiting for more options. A recent realtor.com survey shows more sellers are planning to list their homes this winter, meaning more choices will likely be available soon.

What Does That Mean for You?

Even if your options improve some this season, it won’t significantly shift market conditions overnight. According to NAR, many more listings need to be available to move closer to a more neutral market:

“Given the average monthly demand . . . , 3.55 million homes should be on the market to meet a level of inventory equal to six months of demand, implying a shortage of homes for sale of 2.24 million.”

So remember, even with more homes expected to come to market this season, competition among buyers will remain fierce as there still won’t be enough homes for sale to meet the current demand. That means you’ll need to act quickly when you’re ready to make an offer.

Bottom Line

If you’re planning on buying a home this winter, more options are welcome news, but it doesn’t mean you should slow down. Let’s connect today so you have an expert on your side to help act as quickly as possible when the right home for you hits the market.

Posted in Buying a Home
Dec. 21, 2021

2022 Housing Market Forecast

2022 Housing Market Forecast [INFOGRAPHIC] | MyKCM

Some Highlights

  • What does the coming year hold for the housing market? Here’s what experts project for 2022.
  • Mortgage rates are projected to rise and so are home prices. Experts are forecasting buyer demand will remain strong as people try to capitalize on rates and prices before they climb, creating another strong year for home sales.
  • Let’s connect so you can make your best move in the new year.
Posted in Buying a Home
Dec. 16, 2021

What Everyone Wants To Know: Will Home Prices Decline in 2022?

What Everyone Wants To Know: Will Home Prices Decline in 2022? | MyKCM

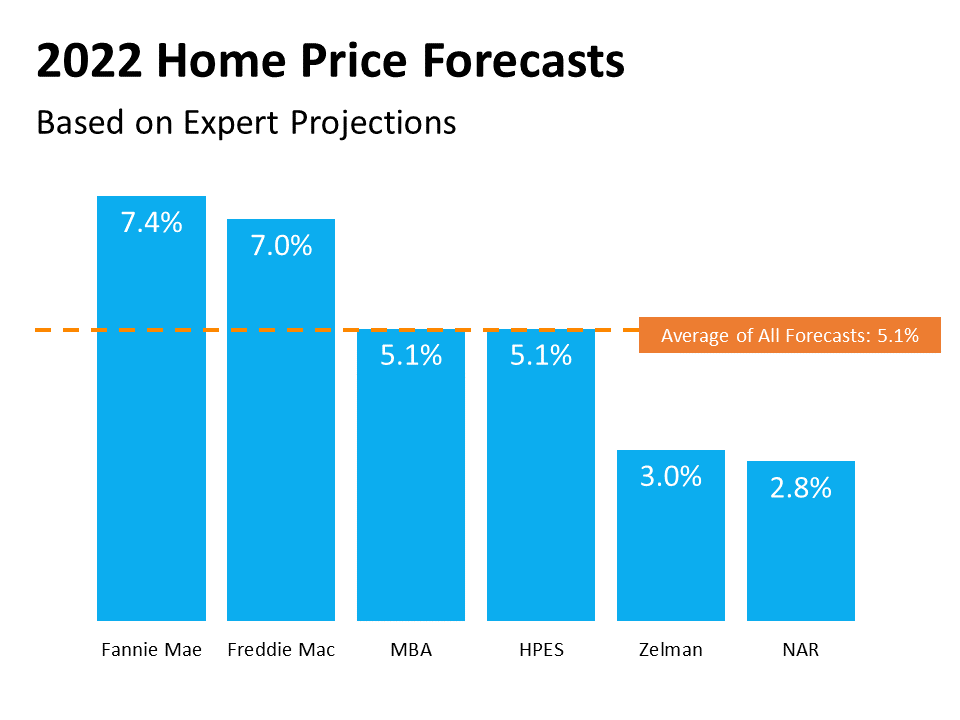
If you’re thinking of buying a home in today’s housing market, you may be wondering how strong your investment will be. You might be asking yourself: if I buy a home now, will it lose value? Or will it continue to appreciate going forward? The good news is, according to the experts, home prices are not projected to decline. Here’s why.

With buyers still outweighing sellers, home prices are forecast to continue climbing in 2022, just at a slower or more moderate pace. Why the continued increase? It’s the simple law of supply and demand. When there are fewer items on the market than there are buyers, the competition for that item makes prices naturally rise.

And while the number of homes for sale today is expected to improve with more sellers getting ready to list their houses this winter, we’re certainly not out of the inventory woods yet. Thus, the projections show continued appreciation, but at a more moderate rate than what we’ve seen over the past year.

Here’s a look at the latest 2022 expert forecasts on home price appreciation:What Everyone Wants To Know: Will Home Prices Decline in 2022? | MyKCMWhat’s the biggest takeaway from this graph? None of the major experts are projecting depreciation in 2022. They’re all showing an increase in home prices next year.

And here’s what some of the industry’s experts say about how that will play out in the housing market next year:

Brad Hunter of Hunter Housing Economics explains:

“. . . the recent unsustainable rate of home price appreciation will slow sharply. . . . home prices will not decline. . . but they will simply rise at a more sustainable pace.”

Danielle Hale from realtor.com agrees:

Price growth is expected to move back toward a normal range, but this is on top of recent high prices, . . . So prices will [still] hit new highs. . . . The pace of price growth is going to slow notably . . . ”

What Does This Mean for the Housing Market?

While home price appreciation is expected to continue, it isn’t projected to be the record-breaking 18 to almost 20% increase the market saw over the past 12 months. Overall, it’s important to note that price increases won’t be as monumental as they were in 2021 – but they certainly won’t decline anytime soon.

What Does That Mean for You?

With motivated buyers in the market and so few homes available to purchase, the imbalance of supply and demand will continue to put upward pressure on home prices in 2022. And when home price appreciation is in the forecast, that’s a clear indication your investment in homeownership is a sound one.

Bottom Line

It’s important to know that home prices are not projected to decline in the new year. Instead, they’re forecast to rise, just at more moderate pace. Let’s connect to make sure you’re up to date on what’s happening with home price appreciation in our market, so you can make an informed decision about your next move.

Posted in Real Estate News
Dec. 14, 2021

If You Think the Housing Market Will Slow This Winter, Think Again.

If You Think the Housing Market Will Slow This Winter, Think Again. | MyKCM

From the opportunity to take advantage of today’s low mortgage rates to changing homeowner needs, Americans have more motivation than ever to buy a home. According to the experts, buyers are making moves right now, creating an unseasonably strong housing market for this time of year.

As we wrap up the fall season and move into the winter months, here’s a look at what several industry leaders have to say about the continued momentum in the current market, and what it means as we head into the early part of next year.

Lawrence Yun, Chief Economist, National Association of Realtors (NAR)

“This solid buying is a testament to demand still being relatively high, as it is occurring during a time when inventory is still markedly low. The notable gain in October assures that total existing-home sales in 2021 will exceed 6 million, which will shape up to be the best performance in 15 years.” 

Odeta Kushi, Deputy Chief Economist, First American

“So far in November, purchase applications point to another strong month in sales. Still low rates and demographic demand support this strength, even as affordability and inventory headwinds remain.”

The M Report

“The demand for housing in the United States has reached a fever pitch, a trend that opposes the norm of this time of the year when the market cools as the winter months set in.”

Mark Fleming, Chief Economist, First American

Strong demographic demand will continue to act as the wind in the housing market’s sails.”

What does this mean for the winter housing market?

Buyers are actively in the market, and they’re competing for homes to purchase. With the momentum coming out of this fall, all signs point to the winter housing market picking up steam, making it much busier than in a more typical year. And as we’ve seen in so many ways, 2020 and 2021 were anything but typical in real estate. It looks like 2022 may be joining that list before we know it.

Bottom Line

If you think the housing market will slow down this winter, think again. Whether you’re thinking of buying a home, selling your house, or both – let’s connect to determine if this winter is your best time to make a move too.

Posted in Real Estate News
Dec. 10, 2021

A Happy Tail: Pets and the Homebuying Process

A Happy Tail: Pets and the Homebuying Process [INFOGRAPHIC] | MyKCM

Some Highlights

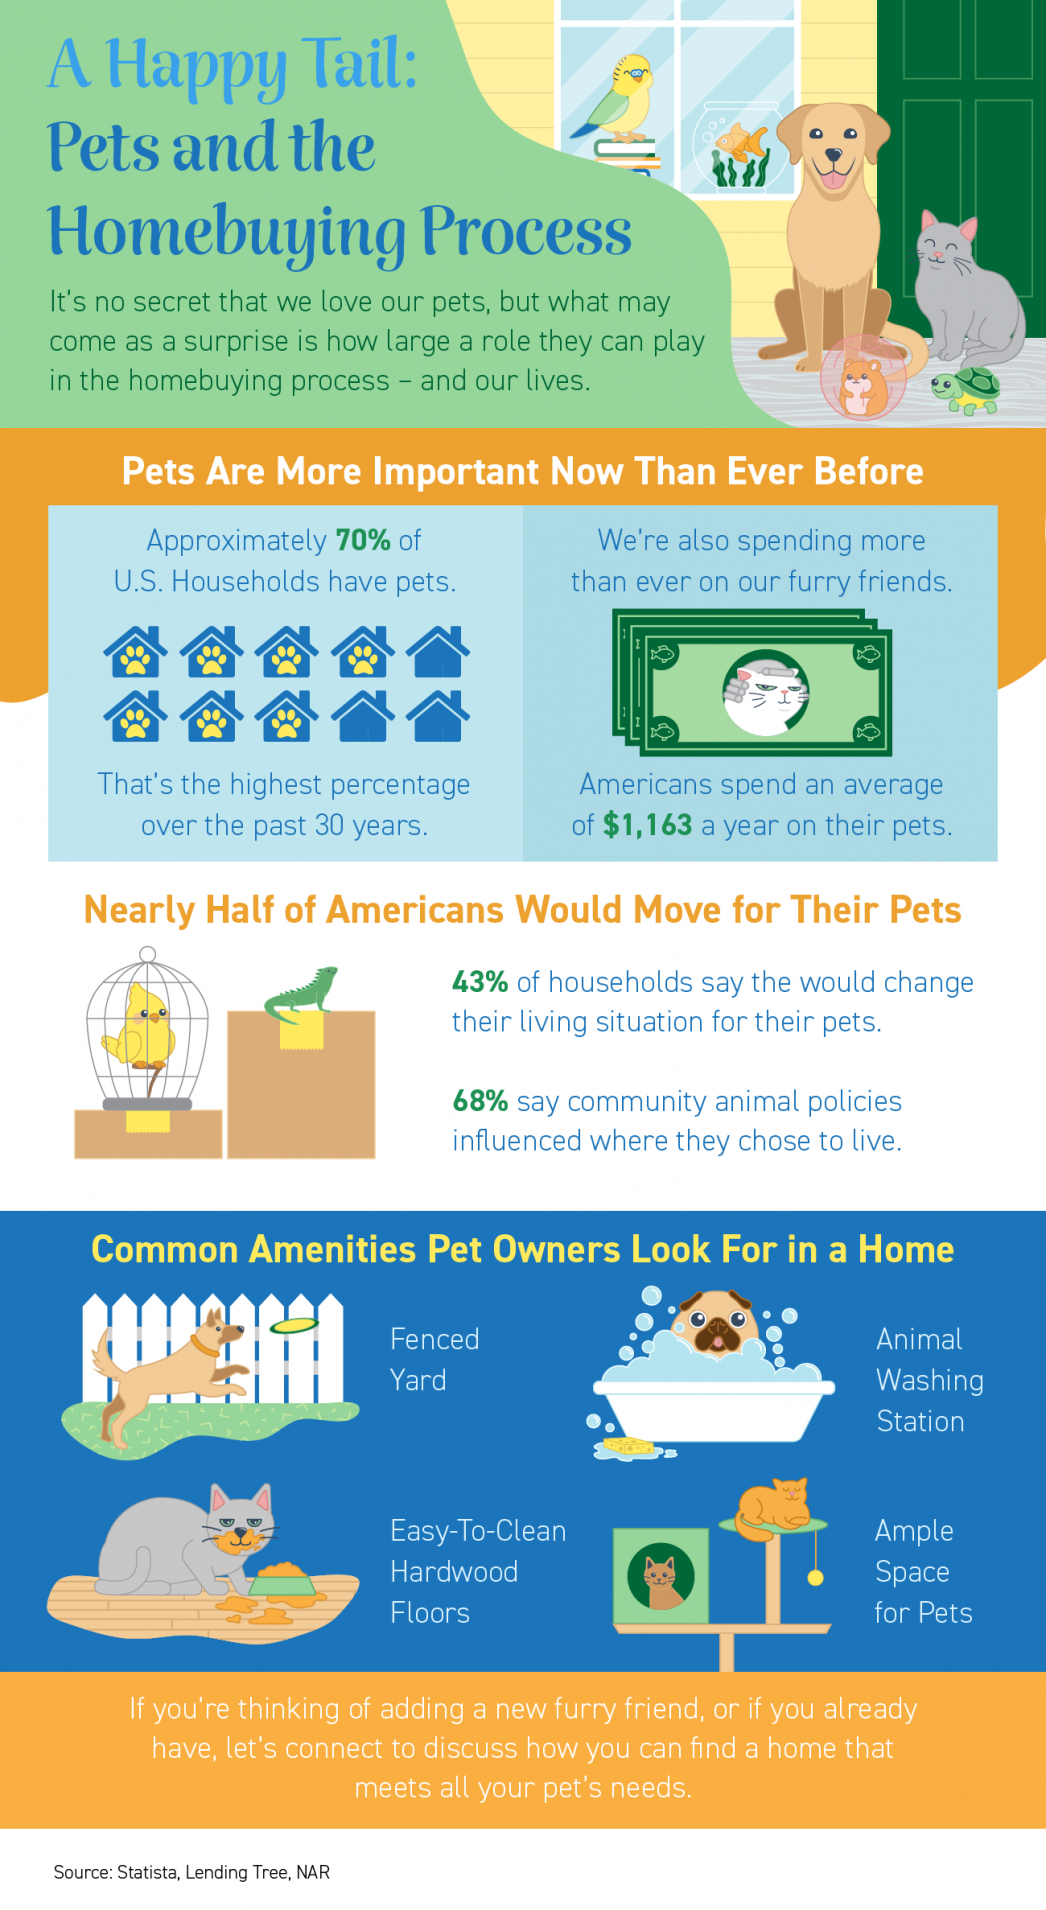
  • It’s no secret that we love our furry friends - about 70% of U.S. households have pets. What may come as a surprise is how large a role they play in the homebuying process.
  • Americans spend $1,163 a year on their pets, and nearly half of pet owners say they would move for better accommodations and amenities for their pets.
  • If you’re thinking of adding a furry friend, or if you already have, let’s connect to discuss how you can find a home that meets all your pet’s needs.
Posted in Buying a Home
Dec. 9, 2021

Two Reasons Why Waiting To Buy a Home Will Cost You

Two Reasons Why Waiting To Buy a Home Will Cost You | MyKCM

If you’re a homeowner who’s decided your current house no longer fits your needs, or a renter with a strong desire to become a homeowner, you may be hoping that waiting until next year could mean better market conditions to purchase a home.

To determine whether you should buy now or wait another year, you can ask yourself two simple questions:

  1. Where will home prices be a year from now?
  2. Where will mortgage rates be a year from now?

Let’s shed some light on the answers to both of these questions.

Where Will Home Prices Be a Year from Now?

Three major housing industry entities are projecting ongoing home price appreciation in 2022. Here are their forecasts:

According to the National Association of Realtors (NAR), the median price of a home today is $353,900. Using an average of the three price projections above (6.53%), a home that sold for $353,900 today would be valued at $377,010 at the end of next year. As a prospective buyer, you would therefore pay an additional $23,110 by waiting.

Where Will Mortgage Rates Be a Year from Now?

Today, Freddie Mac estimates the average 30-year fixed mortgage rate in the fourth quarter of this year will be 2.8%. However, most experts believe mortgage rates will rise as the economy recovers. Here are the forecasts for the fourth quarter of 2022 by the three major entities mentioned above:

That averages out to 3.73% if you include all three forecasts. Any increase in mortgage rates will increase your costs.

What Does It Mean for You if Home Values and Mortgage Rates Increase?

If both variables increase, you’ll pay a lot more in mortgage payments each month. Let’s assume you purchase a $353,900 home in the fourth quarter of this year with a 30-year fixed-rate loan at 2.8% after making a 10% down payment. According to mortgagecalculator.net, your monthly mortgage payment would be approximately $1,309 (this does not include insurance, taxes, and other fees because those vary by location).

That same home one year from now could cost $377,010, and the mortgage rate could be 3.73% (based on the industry forecasts mentioned above). Your monthly mortgage payment after putting down 10%, would be approximately $1,568.Two Reasons Why Waiting To Buy a Home Will Cost You | MyKCMThe difference in your monthly mortgage payment would be $259. That’s $3,108 more per year and $93,240 over the life of the loan.

Add to that the approximately $23,110 a house with a similar value would build in home equity this year due to home price appreciation, and the total net worth increase you could gain by buying this year is over $115,000 (the $93,240 mortgage savings plus the $23,110 potential gain in equity if you buy now).

Bottom Line

When asking if you should buy a home, you may think of the non-financial benefits of homeownership. When asking when to buy, the financial benefits make it clear that doing so now is much more advantageous than waiting until next year.