Northern Virginia Real Estate and Community News

April 25, 2021

This Isn’t a Bubble. It’s Simply Lack of Supply

This Isn’t a Bubble. It’s Simply Lack of Supply. [INFOGRAPHIC] | MyKCM

Some Highlights

  • In a recent article, Lawrence Yun, Chief Economist for the National Association of Realtors (NAR), discussed the state of today’s housing market.
  • When addressing whether or not today’s high buyer competition and rising home prices are evidence of a housing bubble, Yun said that this “is not a bubble. It is simply lack of supply.”
  • Today’s housing market is healthy, and rising prices are driven by real buyer demand. Let’s connect to talk about the best ways to navigate such an energetic market.
April 21, 2021

Planning to Move? You Can Still Secure a Low Mortgage Rate on Your Next Home

Planning to Move? You Can Still Secure a Low Mortgage Rate on Your Next Home | MyKCM

This year, mortgage rates have started to slowly climb above recent record-breaking lows. Many homeowners planning to move may feel like they’ve missed the chance to score a great rate on their next mortgage. In reality, there’s still time to secure a rate far below the historic norm. Here’s why.

After creeping up for seven consecutive weeks, average mortgage rates have dropped more recently (See graph below). With rates taking a slight dip over the past two weeks at the same time the inventory of houses for sale is so low, homeowners today are sitting in the optimal seat to sell. What’s the advantage of selling your house now? Securing a low mortgage rate on your next home.Planning to Move? You Can Still Secure a Low Mortgage Rate on Your Next Home | MyKCMTo take advantage of today’s real estate market, experts are encouraging homeowners to act now before interest rates climb. Danielle Hale, Chief Economist at realtor.com, explains:

…mortgage rates slid for a second week ... but we don’t expect rates to stay at this level for too long.”

Hale continues to say:

“For sellers, getting in early optimizes odds of a quick sale at a good price before there’s too much competition, but that means acting now … In this environment, sellers probably really can’t go wrong, and that’s especially true in the nation’s hottest housing markets where homes are selling quickly and getting the greatest number of viewers online.”

Most experts agree that rates will continue to trend upward. Sam Khater, Chief Economist at Freddie Mac, states:

Despite the pause in mortgage rates recently, we expect them to increase modestly for the remainder of this year.”

In addition, Freddie Mac recently released their Quarterly Forecast, which notes:

We forecast that mortgage rates will continue to rise through the end of next year. We estimate the 30-year fixed mortgage rate will average 3.4% in the fourth quarter of 2021, rising to 3.8% in the fourth quarter of 2022.” (See graph below):

Planning to Move? You Can Still Secure a Low Mortgage Rate on Your Next Home | MyKCMWhile buyers everywhere want to secure the lowest rate possible, it’s important to remember that today’s rates are still much lower than the historic norm. Odeta Kushi, Deputy Chief Economist at First Americanemphasizes:

“While mortgage rates have trended up in recent months, they are still historically low, so relative to one year ago, housing actually is still more affordable and that’s really thanks to this low mortgage rate environment we find ourselves in.”

Bottom Line

If you’re thinking of moving, don’t miss the opportunity to score a great rate on your next home mortgage. Let’s connect today so you can get your house ready to sell and find your dream home while mortgage rates are still low.

Posted in Buying a Home
April 20, 2021

82,338 Great Reasons to Buy a Home Today

82,338 Great Reasons to Buy a Home Today | MyKCM

The financial benefits of buying a home as compared to renting one are always up for debate. However, one element of the equation is often ignored – the ability to build wealth as a homeowner.

Most experts are calling for home prices to continue appreciating over the next several years. The most recent Home Price Expectation Survey, a survey of over one hundred economists, real estate experts, and investment and market strategists, expects home appreciation to increase as follows:

  • 2021: 6%
  • 2022: 4.5%
  • 2023: 4%
  • 2024: 3.6%
  • 2025: 3.5%

Using their annual projections, the graph below shows the equity build-up a purchaser could earn, using a $350,000 home as an example:82,338 Great Reasons to Buy a Home Today | MyKCMA homeowner could increase their net worth by over $80,000 in five years. That’s an average of $16,000 annually. That number should be in any equation determining the financial benefits of owning a home compared to renting.

Bottom Line

Homeowners are going to make a substantial amount of money in home equity over the next five years. If you’re ready to buy a home, let’s connect so you can enjoy this great benefit as well.

April 19, 2021

How Much Time Do You Need To Save for a Down Payment?

How Much Time Do You Need To Save for a Down Payment? | MyKCM

One of the biggest hurdles homebuyers face is saving for a down payment. As you’re budgeting and planning for your home purchase, you’ll want to understand how much you’ll need to put down and how long it will take you to get there. The process may actually move faster than you think.

Using data from the U.S. Department of Housing and Urban Development (HUD) and Apartment List, we can estimate how long it might take someone earning the median income and paying the median rent to save up for a down payment on a median-priced home. Since saving for a down payment can be a great time to practice budgeting for housing costs, this estimate also uses the concept that a household should not pay more than 28% of their total income on monthly housing expenses.

According to the data, the national average for the time it would take to save for a 10% down payment is right around two and a half years (2.53). Residents in Iowa can save for a down payment the fastest, doing so in just over one year (1.31). The map below illustrates this time (in years) for each state:How Much Time Do You Need To Save for a Down Payment? | MyKCM

What if you only need to save 3%?

What if you’re able to take advantage of one of the 3% down payment programs available? It’s a common misconception that you need a 20% down payment to buy a home, but there are actually more affordable options and down payment assistance programs available, especially for first-time buyers. The reality is, saving for a 3% down payment may not take several years. In fact, it could take less than a year in most states, as shown in the map below:How Much Time Do You Need To Save for a Down Payment? | MyKCM

Bottom Line

Wherever you are in the process of saving for a down payment, you may be closer to your dream home than you think. Let’s connect to explore the down payment options available in our area and how they support your plans.


April 17, 2021

Your Tax Refund and Stimulus Checks May Help You Reach Your Homeownership Goals

Posted in Buying a Home
April 16, 2021

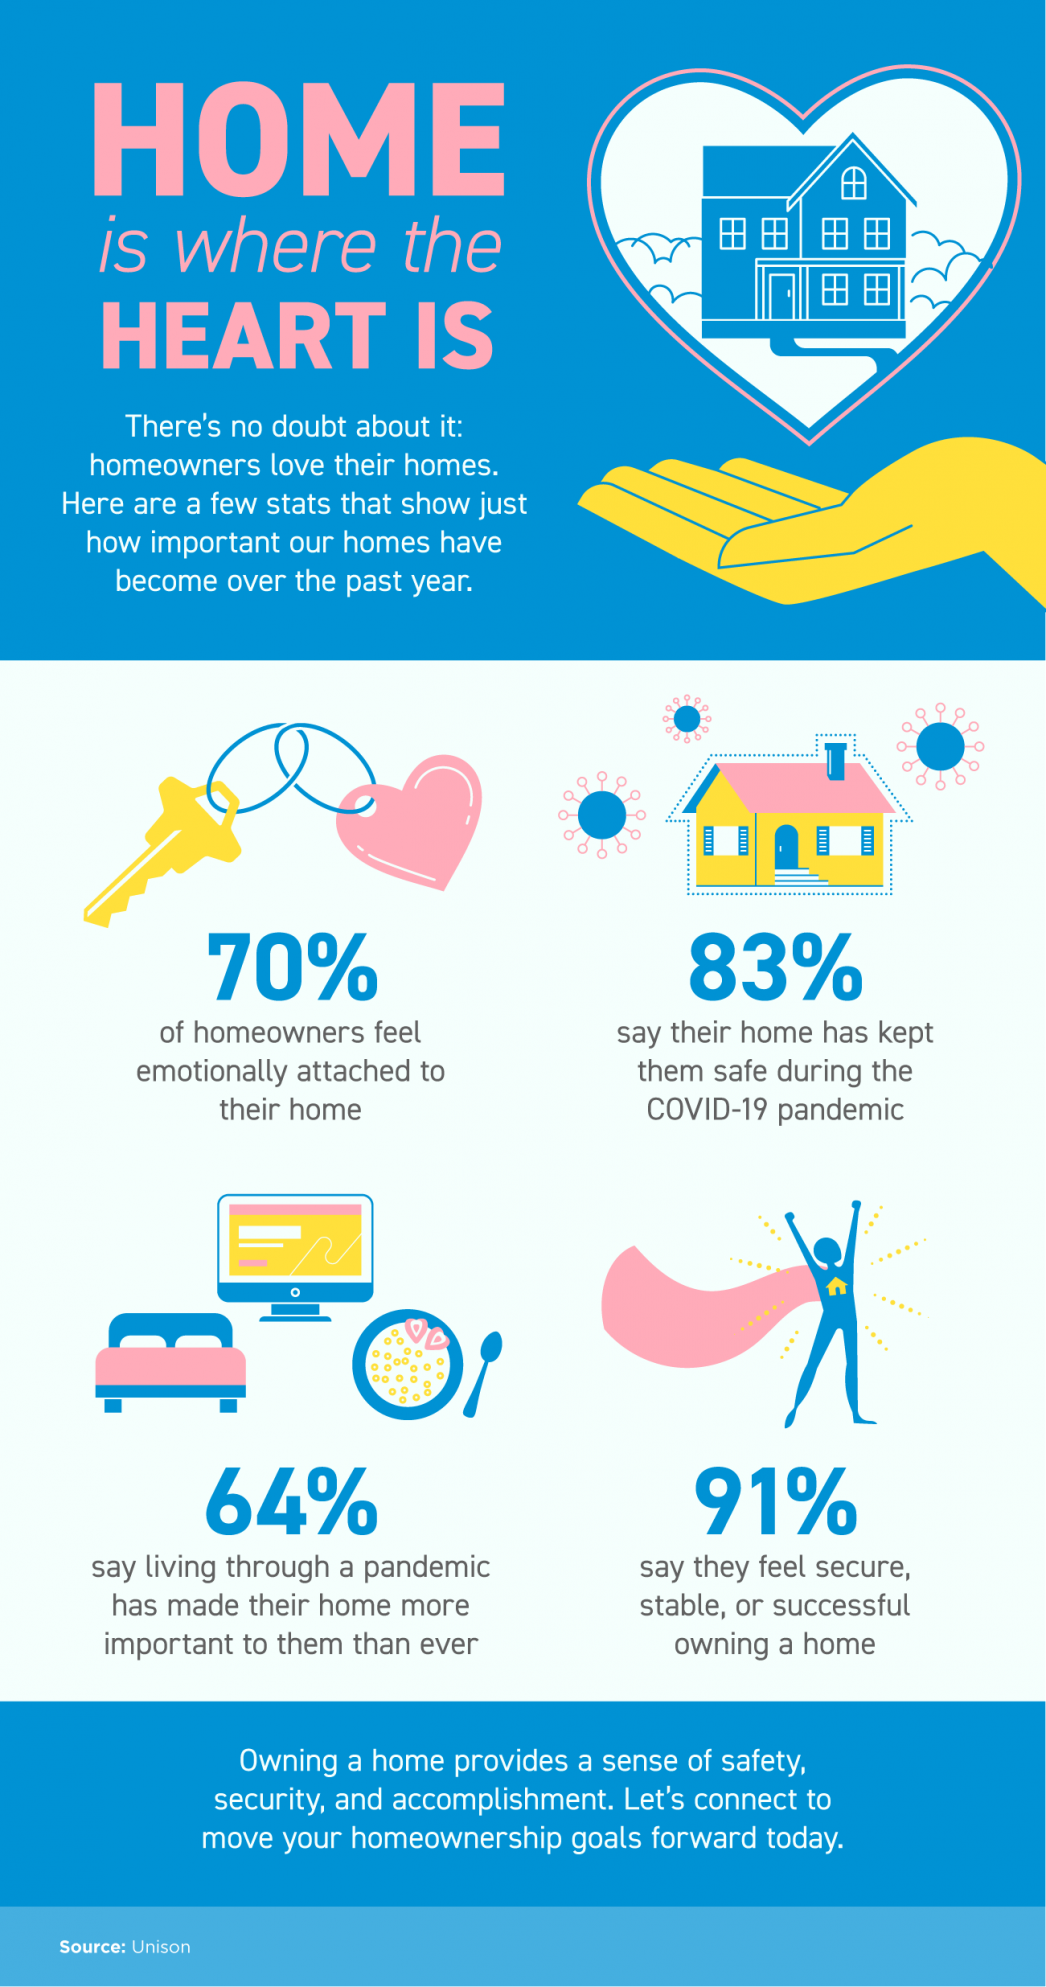
Home Is Where the Heart Is

Home Is Where the Heart Is [INFOGRAPHIC] | MyKCM

Some Highlights

  • There’s no doubt about it: homeowners love their homes, and that feeling has become even more important over the past year.
  • The vast majority of homeowners say they’re emotionally attached to their home and that it has kept them safe during the COVID-19 pandemic.
  • Owning a home provides a sense of safety, security, and accomplishment. Let’s connect to move your homeownership goals forward today.
Posted in Real Estate News
April 15, 2021

93% of Americans Believe a Home Is a Better Investment Than Stocks

93% of Americans Believe a Home Is a Better Investment Than Stocks | MyKCM

A recent Survey of Consumer Finances study released by the Federal Reserve reveals the net worth of homeowners is forty times greater than that of renters. If you’re wondering if homeownership is a good investment, the study clearly answers that question, and the answer is yes.

Do Americans believe a home is a better investment than stocks?

In a post on the Liberty Street Economics blog, the Federal Reserve Bank of New York notes that 93.3% of Americans believe buying a home is definitely or probably a better investment than buying stocks.

Here’s how the results break down:93% of Americans Believe a Home Is a Better Investment Than Stocks | MyKCMThe survey also shows a wide range of reasons why Americans feel that way (respondents were able to pick more than one answer):93% of Americans Believe a Home Is a Better Investment Than Stocks | MyKCM

Bottom Line

The data show how strongly Americans believe in homeownership as an investment. That belief is warranted. The Liberty Street Economics blog put it best by saying:

“Housing represents the largest asset owned by most households and is a major means of wealth accumulation, particularly for the middle class.”

Posted in Buying a Home
April 12, 2021

4 Major Reasons Households in Forbearance Won’t Lose Their Homes to Foreclosure

4 Major Reasons Households in Forbearance Won’t Lose Their Homes to Foreclosure | MyKCM

There has been a lot of discussion as to what will happen once the 2.3 million households currently in forbearance no longer have the protection of the program. Some assume there could potentially be millions of foreclosures ready to hit the market. However, there are four reasons that won’t happen.

1. Almost 50% Leave Forbearance Already Caught Up on Payments

According to the Mortgage Bankers Association (MBA), data through March 28 show that 48.9% of homeowners who have already left the program were current on their mortgage payments when they exited.

  • 6% made their monthly payments during their forbearance period
  • 7% brought past due payments current
  • 6% paid off their loan in full

This doesn’t mean that the over two million still in the plan will exit exactly the same way. It does, however, give us some insight into the possibilities.

2. The Banks Don’t Want the Houses Back

Banks have learned lessons from the crash of 2008. Lending institutions don’t want the headaches of managing foreclosed properties. This time, they’re working with homeowners to help them stay in their homes.

As an example, about 50% of all mortgages are backed by the Federal Housing Finance Agency (FHFA). In 2008, the FHFA offered 208,000 homeowners some form of Home Retention Action, which are options offered to a borrower who has the financial ability to enter a workout option and wants to stay in their home. Home retention options include temporary forbearances, repayment plans, loan modifications, or partial loan deferrals. These helped delinquent borrowers stay in their homes. Over the past year, the FHFA has offered that same protection to over one million homeowners.

Today, almost all lending institutions are working with their borrowers. The report from the MBA reveals that of those homeowners who have left forbearance,

  • 5% have worked out a repayment plan with their lender
  • 5% were granted a loan deferral where a borrower does not have to pay the lender interest or principal on a loan for an agreed-to period of time
  • 9% were given a loan modification

3. There Is No Political Will to Foreclose on These Households

The government also seems determined not to let individuals or families lose their homes. Bloomberg recently reported:

“Mortgage companies could face penalties if they don’t take steps to prevent a deluge of foreclosures that threatens to hit the housing market later this year, a U.S. regulator said. The Consumer Financial Protection Bureau (CFPB) warning is tied to forbearance relief that’s allowed millions of borrowers to delay their mortgage payments due to the pandemic…mortgage servicers should start reaching out to affected homeowners now to advise them on ways they can modify their loans.”

The CFPB is proposing a new set of guidelines to ensure people will be able to retain their homes. Here are the major points in the proposal:

The proposed rule would provide a special pre-foreclosure review period that would generally prohibit servicers from starting foreclosure until after December 31, 2021.

The proposed rule would permit servicers to offer certain streamlined loan modification options to borrowers with COVID-19-related hardships based on the evaluation of an incomplete application.

The proposal rule wants temporary changes to certain required servicer communications to make sure borrowers receive key information about their options at the appropriate time.

A final decision is yet to be made, and some do question whether the CFPB has the power to delay foreclosures. The entire report can be found hereProtections for Borrowers Affected by the COVID-19 Emergency Under the Real Estate Settlement Procedures Act (RESPA), Regulation X.

4. If All Else Fails, Homeowners Will Sell Their Homes Before a Foreclosure

Homeowners have record levels of equity today. According to the latest CoreLogic Home Equity Report, the average equity of mortgaged homes is currently $204,000. In addition, 38% of homes do not have a mortgage, so the level of equity available to today’s homeowners is significant.

Just like the banks, homeowners learned a lesson from the housing crash too.

“In the same way that grandparents and great grandparents were shaped by the Great Depression, much of the public today remembers the 2006 mortgage meltdown and the foreclosures, unemployment, and bank failures it created. No one with any sense wants to repeat that experience...and it may explain why so much real estate equity remains mortgage-free.”

What does that mean to the forbearance situation? According to Black Knight:

“Just one in ten homeowners in forbearance has less than 10% equity in their home, typically the minimum necessary to be able to sell through traditional real estate channels to avoid foreclosure.”

Bottom Line

The reports of massive foreclosures about to come to the market are highly exaggerated. As Ivy Zelman, Chief Executive Officer of Zelman & Associates with roughly 30 years of experience covering housing and housing-related industries, recently proclaimed:

“The likelihood of us having a foreclosure crisis again is about zero percent.”
 

Posted in Real Estate News
April 7, 2021

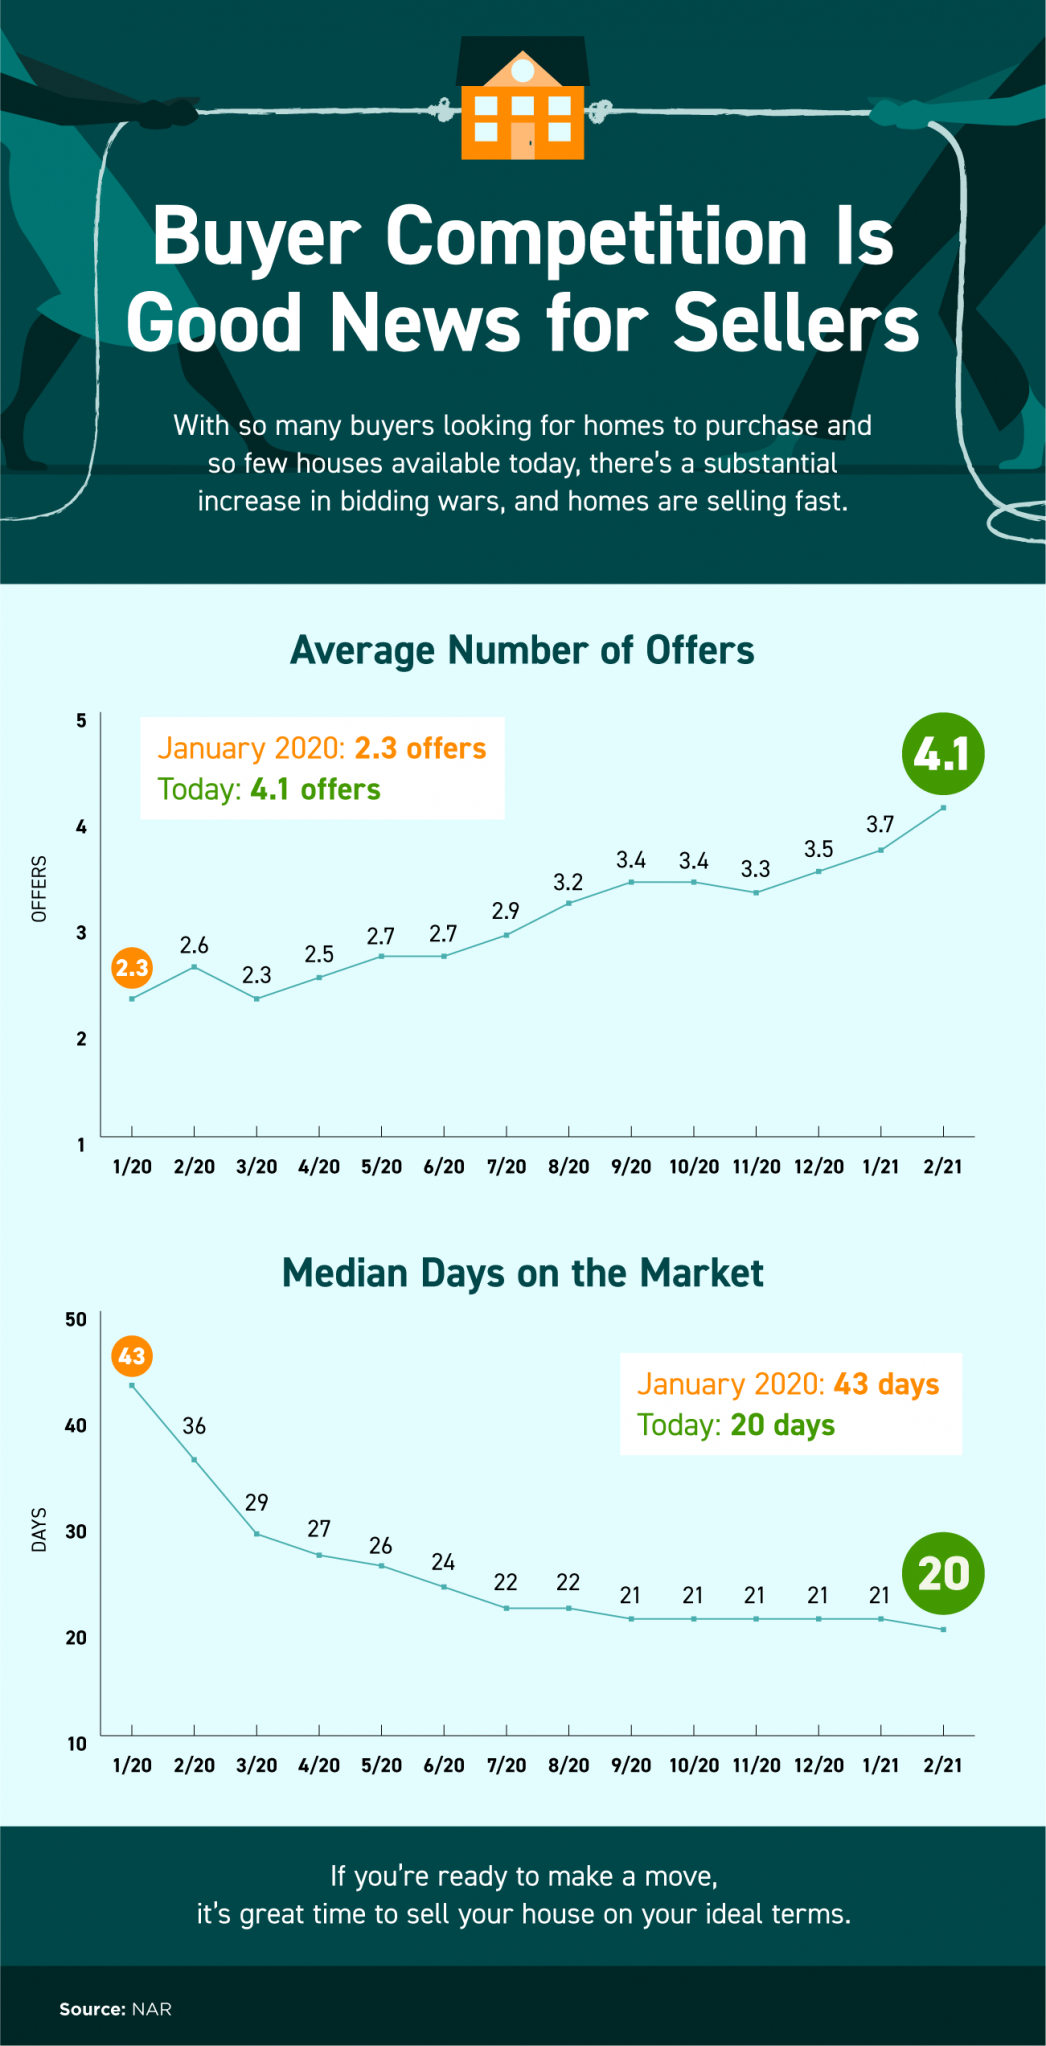
Buyer Competition Is Good News for Sellers

Buyer Competition Is Good News for Sellers [INFOGRAPHIC] | MyKCM

Some Highlights

  • With so many buyers looking for homes to purchase and so few houses available today, there’s a substantial increase in bidding wars, and homes are selling fast.
  • According to the latest Realtors Confidence Index Survey from the National Association of Realtors (NAR), on average, houses are receiving over four offers from buyers and they’re selling in less than three weeks.
  • If you’re ready to make a move, let’s connect today so you can sell your house while the market is in your favor.
April 6, 2021

Don’t Sell on Your Own Just Because It’s a Sellers’ Market

Don’t Sell on Your Own Just Because It’s a Sellers’ Market | MyKCM

In a sellers’ market, some homeowners might be tempted to try to sell their house on their own (known as For Sale By Owner, or FSBO) instead of working with a trusted real estate professional. When the inventory of homes for sale is as low as it is today, buyers are eager to snatch up virtually any house that comes to market. This makes it even more tempting to FSBO. As a result, some sellers think selling their house will be a breeze and see today’s market as an opportunity to FSBO. Let’s unpack why that’s a big mistake and may actually cost you more in the long run.

According to the Profile of Home Buyers and Sellers published by the National Association of Realtors (NAR), 41% of homeowners who tried to sell their house as a FSBO did so to avoid paying a commission or fee. In reality, even in a sellers’ market, selling on your own likely means you’ll net a lower profit than when you sell with the help of an agent.

The NAR report explains:

FSBOs typically sell for less than the selling price of other homes; FSBO homes sold at a median of $217,900 in 2020 (up from $200,000 in 2019), and still far lower than the median selling price of all homes at $242,300. Agent-assisted homes sold for a median of $295,000...Sellers who began as a FSBO, then ended up working with an agent, received 98 percent of the asking price, but had to reduce their price the most before arriving at a final listing price.”

When the seller knew the buyer, that amount was even lower, coming in at $176,700 (See graph below):Don’t Sell on Your Own Just Because It’s a Sellers’ Market | MyKCMThat’s a lot of money to risk losing when you FSBO – far more than what you’d save on commission or other fees. Despite the advantages sellers have in today’s market, it’s still crucial to have the support of an expert to guide you through the process. Real estate professionals are trained negotiators with a ton of housing market insights that average homeowners may never have. An agent’s expertise can alleviate much of the stress of selling your house and help you close the best possible deal when you do.

Bottom Line

If you’re ready to sell your house this year and you’re considering doing so on your own, be sure to think through that decision carefully. Odds are, you stand to gain the most by working with a knowledgeable and experienced real estate agent. Let’s connect to discuss how a trusted advisor can help you, especially in today’s market.

Posted in Selling Your Home